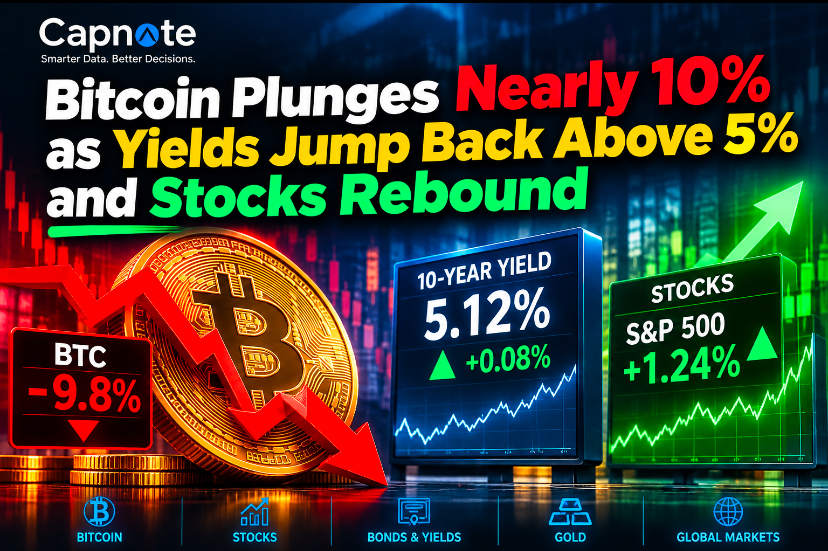
Bitcoin Plunges Nearly 10% as Yields Jump Back Above 5% and Stocks Rebound
Here’s where the key indicators sit versus their own history, plus the best and worst movers across companies and industries — and the risk and growth factors that may sit behind them. We don’t tell you what to do. We just show you what the data says, then close each section with a quick Read: the possible drivers, and what they could mean.
SUBSCRIBER OFFER
$100 Lifetime Access — Pay Once, Keep It for Good
Get full Capnote Professional — every indicator, factor and screen — for a single one-time payment of $100. No renewals, no annual bill, ever. Get lifetime access →
01 · COMPANIES
Movers Above $10B Market Cap
▲ LEADERS
1 WEEK
- Cerebras Systems Inc. Class A Common Stock — +12.71%
- Zoom Video Communications Inc — +9.12%
- SK Telecom Co Ltd ADR — +6.31%
YEAR TO DATE
- Life Time Group Holdings Inc — +74.18%
- Cloudflare Inc — +55.16%
- Airbnb Inc — +40.78%
YEAR ON YEAR
- Seagate Technology PLC — +103.26%
- Permian Resources Corporation — +79.40%
- Arrow Electronics Inc — +75.10%
Capnote tip: common growth factors among top YTD names include positive EBITDA margin, positive profit margin, and return on invested capital expansion.
▼ LAGGARDS
1 WEEK
- Pershing Square Inc. — -14.30%
- First Solar Inc — -11.45%
- NVR Inc — -6.99%
YEAR TO DATE
- Zoetis Inc — -31.59%
- Circle Internet Group, Inc. — -25.51%
- Ryanair Holdings PLC ADR — -19.18%
YEAR ON YEAR
- Fidelity National Information Services Inc — -53.41%
- Pentair PLC — -34.50%
- Leidos Holdings Inc — -30.99%
Capnote tip: common risk factors among these YTD laggards include macroeconomic decline or recession, competition intensity & availability of substitutes, and change in customer demand or preferences.
THE READ
Possible drivers: Cerebras Systems (+12.71%) tops the weekly leaderboard just three weeks after appearing on the weekly laggard list (-7.26% on Oct 24), a sharp reversal. Zoom (+9.12%) and SK Telecom (+6.31%) follow. On the downside, Pershing Square’s -14.30% is the steepest large-cap drop, a turnaround from its +24.67% weekly gain in September. Circle Internet Group, the stablecoin issuer, sits on the YTD laggard board (-25.51%) in a week when crypto sold off sharply.
What it could mean: Cerebras and Pershing Square both swinging hard in opposite directions points to stock-specific volatility rather than a market-wide theme. Fidelity National Information Services remains at the bottom of the YoY board for a second straight week (-53.41%), and Zoetis is back at the bottom of the YTD board (-31.59%) for the third time in the last six reports.
02 · COMPANIES
Movers Below $10B Market Cap
▲ LEADERS
1 WEEK
- Babcock & Wilcox Enterprises Inc — +24.69%
- Pangaea Logistic — +16.78%
- ADTRAN Inc — +16.09%
YEAR TO DATE
- Entravision Communications — +225.06%
- Amylyx Pharmaceuticals Inc — +166.02%
- Day One Biopharmaceuticals Inc — +144.84%
YEAR ON YEAR
- Entravision Communications — +254.47%
- Kelly Services B Inc — +200.42%
- Lindblad Expeditions Holdings Inc — +187.35%
Capnote tip: common growth factors among top YTD names include return on invested capital expansion, revenue growth from last year, and net margin expansion from last year.
▼ LAGGARDS
1 WEEK
- P3 Health Partners Inc — -34.75%
- Janus International Group Inc — -21.43%
- Ginkgo Bioworks Holdings — -20.23%
YEAR TO DATE
- Suja Life, Inc. Class A Common Stock — -97.66%
- BOXABL Inc. — -86.73%
- Verra Mobility Corp — -85.74%
YEAR ON YEAR
- Suja Life, Inc. Class A Common Stock — -97.66%
- Verra Mobility Corp — -91.25%
- BOXABL Inc. — -86.65%
Capnote tip: common risk factors among these YTD laggards include competition intensity & availability of substitutes, macroeconomic decline or recession, and adverse capital markets access.
THE READ
Possible drivers: Entravision Communications sweeps both the YTD (+225.06%) and YoY (+254.47%) boards, and Babcock & Wilcox leads the week at +24.69%. Ginkgo Bioworks, a weekly leader on Oct 3 (+22.66%), now sits on the weekly laggard list (-20.23%). Suja Life tops both the YTD and YoY laggard boards for a tenth straight report, and Verra Mobility’s YoY loss deepened again to -91.25%, a new low in our data.
What it could mean: Ginkgo’s round trip from leader to laggard in six weeks is a reminder of how volatile small-cap biotech can be. Verra Mobility’s steady slide, now at its worst reading in our data for the second straight report, looks like a sustained decline rather than noise.
03 · INDUSTRIES
Industry Performance
Weighted-average market cap of listed companies using Capnote’s proprietary groupings.
▲ HIGHEST PERFORMING
1 WEEK
- Space Logistics — +30.79%
- Data Management — +11.37%
- Computer Hardware — +5.22%
YEAR TO DATE
- Admin & Legal — +60.43%
- Accounting — +55.84%
- Scientific Services & Tools — +50.61%
YEAR ON YEAR
- Operator — +78.11%
- Refining & Smelting — +67.42%
- Admin & Legal — +57.07%
Capnote tip: common growth factors among top YTD industries include macroeconomic stability & growth, technology access & trends, and product or service characteristics & qualities.
▼ LOWEST PERFORMING
1 WEEK
- Fabrication — -6.72%
- Wood Products — -4.32%
- Distribution — -3.29%
YEAR TO DATE
- Holding Company — -90.26%
- Children — -44.62%
- Recycling — -41.90%
YEAR ON YEAR
- Holding Company — -90.74%
- Children — -56.68%
- Recycling — -54.76%
Capnote tip: common risk factors among these YTD laggard industries include reputation or brand decline and impairment, competition intensity & availability of substitutes, and adverse capital markets access.
THE READ
Possible drivers: Space Logistics jumped 30.79%, its largest weekly gain in our data, after falling 13.16% four weeks ago. Data Management (+11.37%) bounced back after being the weakest industry last week (-7.74%). Refining & Smelting stays out of the weekly top three, and its YoY gain has now fallen for three straight reports, from +88.62% on Oct 24 to +67.42%. Holding Company appears at the bottom of both the YTD (-90.26%) and YoY (-90.74%) boards.
What it could mean: Refining & Smelting’s steady erosion as crude has cooled supports the link we’ve been tracking between the industry and oil. Holding Company’s roughly -90% reading is the most extreme in the industry data, and it’s worth watching whether it reflects a broad decline or a small group of companies carrying the average.
04 · INDICATORS
Where the Big Levels Sit
Positions vs. a 5-year moving average. Level reflects standard deviations from the mean.
| Indicator | 1W % | Last | Level |
|---|---|---|---|
| US 10Y Treasury | +6.05 | 5.15 | High |
| S&P 500 | +2.51 | 7,561.67 | High |
| Hang Seng | -3.45 | 23,637.60 | High |
| Crude Oil (Brent) | -2.28 | 96.08 | High |
| US Dollar Index (DXY) | +1.09 | 103.41 | Average |
| Gold | -4.60 | 3,887.60 | High |
| Bitcoin | -9.90 | 68,243.30 | Average |
THE READ
Possible drivers: Bitcoin fell 9.90% to $68,243, its biggest weekly drop in our data and its sixth straight weekly decline. It also slipped from High to Average, the first time it has dropped below High in our data. Ethereum fell 13.76% to a Low level. The US 10-year Treasury yield jumped 6.05% to 5.15%, its largest weekly rise in our data, ending five straight weeks of declines. The dollar index climbed to 103.41, its highest level in our data. Gold gave back last week’s rebound (-4.60%), and the Hang Seng gave up much of last week’s gain (-3.45%). Brent eased another 2.28% to $96.08, close to its early-September low.
What it could mean: Higher yields and a stronger dollar tend to weigh on assets that don’t pay interest, such as gold and crypto, which may help explain this week’s sell-off in both. What stands out is that the S&P 500 rebounded 2.51%, its largest weekly gain in our data, ending a four-week losing streak even as yields spiked. Whether stocks can keep rising with the 10-year back above 5% is the question for next week.
05 · WEEKLY MOVERS
Biggest Indicator Swings
▲ GAINS SINCE LAST WEEK
- Switzerland 10Y · Average — +25.47%
- Lean Hogs · Very Low — +13.97%
- Oat · Average — +12.65%
- Turkey 10Y · High — +10.19%
- Japan 10Y · Very High — +8.30%
▼ LOSSES SINCE LAST WEEK
- ETH/USD · Low — -13.76%
- BTC/USD · Average — -9.90%
- Gasoline · Average — -6.37%
- Silver · High — -6.34%
- Gold · High — -4.60%
THE READ
Possible drivers: Both major cryptocurrencies top the loss list, with Ethereum (-13.76%) falling harder than Bitcoin (-9.90%). Silver (-6.34%) and Gold (-4.60%) both fell, and Gasoline slid another 6.37% after last week’s -16.43%. On the gain side, government bond yields jumped in several countries, including Japan’s 10-year (+8.30%, now at a Very High level) and Switzerland’s (+25.47%).
What it could mean: Crypto, precious metals and gasoline all falling in the same week, while bond yields rise across several countries, points to a broad tightening move rather than an isolated sell-off. Japan’s 10-year yield reaching Very High is worth watching alongside the US move, since it shows the rise in yields wasn’t confined to the US.
Reply with your read on where we sit in the macro cycle. Featured replies earn some goodies.
Track 145+ indicators and their live positions on our free indicators page.
Market Trend Monday is provided for information only and reflects what the data shows. It is not investment advice, nor a recommendation to buy or sell any security. Figures are drawn from Capnote’s data and methodology and may differ from other sources. Always do your own research.